Blog

How to Prepare a BAS [Step-By-Step Guide]

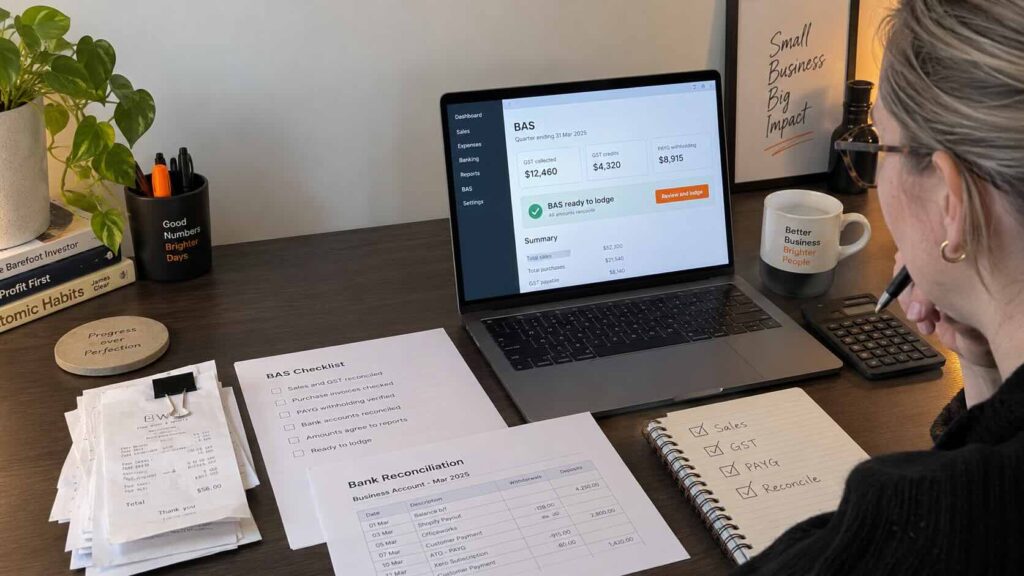
Woman preparing her Business Activity Statement

To prepare a BAS, start by bringing your bookkeeping up to date, reconciling your accounts and checking that sales, purchases, GST and payroll transactions have been recorded correctly for the reporting period. You can then review the relevant BAS figures, investigate any discrepancies and complete the sections that apply to your business before lodging.

A Business Activity Statement can cover more than GST. Depending on your registrations and circumstances, it may also include PAYG withholding, PAYG instalments and other tax obligations. Accurate BAS preparation therefore starts with accurate financial records rather than simply copying figures from accounting software.

This guide explains how to prepare a BAS, what records you may need, how GST figures are calculated, what to check before lodging and when professional bookkeeping or BAS support may be useful.

Quick Summary

  • Bas preparation starts with complete and up-to-date bookkeeping for the relevant reporting period.
  • Bank accounts, credit cards and other relevant accounts should be reconciled before relying on accounting software reports.
  • Check sales, purchases, GST treatment, payroll and PAYG figures rather than assuming automatically generated BAS figures are correct.
  • Your GST accounting basis can affect when sales and purchases are reported on the BAS.
  • The sections you need to complete depend on your business registrations and circumstances, so not every BAS will contain the same obligations.

What Is a BAS?

A Business Activity Statement, or BAS, is a form used to report certain business tax obligations to the Australian Taxation Office (ATO).

A BAS Can Include:

  • Goods and services tax (GST)
  • Pay as you go (PAYG) withholding
  • Payg instalments
  • Fringe benefits tax instalments
  • Wine equalisation tax
  • Luxury car tax.

The sections that appear on your BAS depend on the registrations and obligations attached to your business. A small service business registered for GST and employing staff may therefore have different BAS requirements from another business with no employees or different tax registrations.

Your reporting frequency can also vary. If you are trying to work out when your next statement needs to be submitted, our guide explains when BAS is due and the common reporting cycles.

What Information Do You Need to Prepare a BAS?

The records required will depend on what your business needs to report, but the starting point is generally your bookkeeping for the full BAS period.

You May Need to Review:

  • Sales invoices and other income records
  • Customer payments
  • Supplier bills and expense records
  • Receipts and tax invoices
  • Bank transactions
  • Business credit card transactions
  • Gst collected on taxable sales
  • Gst credits relating to eligible purchases
  • Payroll records
  • Payg withholding amounts
  • Payg instalment information, where applicable
  • Asset purchases and disposals
  • Adjustments or corrections relating to previous transactions.

If you use accounting software such as Xero, much of this information can be brought together automatically. However, accounting software can only report what has been entered into it. Missing transactions, duplicate entries or incorrect tax codes can still produce an incorrect BAS.

Businesses setting up their accounting system for the first time can also review our guide to setting up Xero for a small business.

How to Prepare a BAS Step by Step

A structured process makes it easier to check the underlying records before relying on the final BAS report.

1

Bring Your Bookkeeping up to Date

Record the sales, expenses, payments, receipts and other transactions that belong to the BAS period. Review uncategorised transactions and check that transactions have not been duplicated or omitted.

2

Reconcile Your Accounts

Compare the transactions in your accounting system with your bank accounts, credit cards and other relevant financial accounts. Investigate unmatched transactions, differences in balances and duplicate entries before moving on.

3

Review Sales and GST Collected

Check that sales have been recorded in the correct period and review their GST treatment. Separate taxable, GST-free and other sales where relevant rather than assuming every transaction should be treated in the same way.

4

Check Purchases and GST Credits

Review business purchases and expenses, including the tax code applied to each transaction. Check whether GST was actually included and whether the business is entitled to claim the relevant GST credit.

5

Review PAYG and Other BAS Obligations

If your BAS includes PAYG withholding, PAYG instalments or other tax obligations, compare those figures with the relevant payroll, accounting and ATO records. Only complete the sections that apply to your business.

6

Review the BAS and Lodge

Compare the final BAS figures with your accounting reports and investigate amounts that look unusual. Once the figures have been checked, the BAS can be lodged through an available ATO channel or through an appropriately registered tax or BAS agent.

Example of a Completed BAS

The example below shows how the BAS figures might come together for a fictional Australian small business. It is designed to illustrate the relationship between sales, GST credits, PAYG withholding and the final amount payable. An actual BAS may contain different labels depending on the business’s registrations and reporting obligations.

FICTIONAL EXAMPLE ONLY

Business Activity Statement

Westside Studio Pty Ltd
Quarterly Reporting Period: 1 July to 30 September

Goods and Services Tax

G1 Total sales $88,000
1A Gst on sales $8,000
1B Gst on purchases $5,000

PAYG Withholding

W1 Total salary, wages and other payments $45,000
W2 Amount withheld from payments shown at W1 $8,500
4 Payg tax withheld $8,500

PAYG Income Tax Instalment

5A Payg income tax instalment $2,000

Example BAS Calculation

GST on sales
$8,000
Less GST credits on purchases
-$5,000
Net GST payable
$3,000
PAYG tax withheld
+$8,500
PAYG income tax instalment
+$2,000
Illustrative amount payable
$13,500

This is a fictional example created for illustration only and is not an ATO form. Actual BAS labels, amounts and reporting requirements depend on the business’s registrations and circumstances.

In this example, Westside Studio Pty Ltd collected $8,000 of GST on its taxable sales and had $5,000 of eligible GST credits on purchases. This produces a net GST liability of $3,000.

The business also withheld $8,500 from employee payments and has a $2,000 PAYG income tax instalment for the quarter. With no other credits or obligations included in this simplified example, the illustrative amount payable is $13,500.

The example also shows why the amount payable on a BAS is not simply the difference between GST collected and GST credits. PAYG withholding, PAYG instalments and other applicable obligations can change the final position.

Why Should You Reconcile Your Accounts Before Preparing a BAS?

Reconciliation checks whether the transactions recorded in your accounting system agree with external records such as your bank statement.

For example, your accounting software might show that every supplier expense has been entered, but your bank statement may contain a payment that has not been recorded. If that payment relates to an eligible business purchase, leaving it out could also affect your GST reporting.

The opposite can happen when a transaction has accidentally been entered twice. Your accounting reports may then overstate an expense and potentially the associated GST credit.

Regular account reconciliation helps identify these differences before they flow through to financial reports and activity statements.

How Is GST Calculated on a BAS?

For many GST-registered businesses, two of the key figures are the GST payable on taxable sales and the GST credits available on eligible business purchases.

A Simplified Example Might Look Like This:

  • Gst payable on taxable sales: $8,000
  • Eligible GST credits on purchases: $5,000
  • Net GST amount: $3,000 payable.

This example only shows the GST component. It does not mean that the total amount payable on the BAS would necessarily be $3,000. PAYG withholding, PAYG instalments or other obligations included on the statement can change the final amount.

The GST amount on an ordinary fully taxable sale is commonly one-eleventh of the GST-inclusive price. However, not every sale is taxable and not every business expense gives rise to a full GST credit. The GST treatment needs to reflect the actual transaction.

What Is the Difference Between Cash and Non-Cash GST Accounting?

Your GST accounting basis affects when sales and purchases are included in your BAS.

Cash Basis

Under cash-basis GST accounting, GST is generally attributed as payment is received from customers or made to suppliers.

For example, if an invoice is issued in June but the customer does not pay until July, the timing of the GST reporting may fall into the later period when accounting on a cash basis.

Non-Cash Basis

Under a non-cash basis, sometimes referred to as accrual GST accounting, the timing can be based on when an invoice is issued or payment occurs, depending on the transaction and applicable rules.

This means a business may sometimes report GST before the related customer invoice has actually been paid.

Check the accounting basis registered for your business rather than changing the BAS period simply to match when cash moved through the bank account. The ATO provides further guidance on choosing a GST accounting method.

BAS Preparation Checklist

Before lodging, use this BAS preparation checklist to make sure the underlying records have been reviewed rather than relying solely on an automatically generated BAS report.

Check What to review Why it matters
Bookkeeping complete Sales, purchases, payments and receipts for the full reporting period Missing transactions can change BAS figures
Bank accounts reconciled Accounting balances against bank statements Helps identify missing and duplicate entries
Credit cards reconciled Business credit card purchases and payments Expenses can otherwise be missed or duplicated
Sales reviewed Sales period, GST treatment and unusual transactions Incorrect sales coding can affect GST payable
Purchases reviewed Expenses, GST codes and supporting records Helps support the GST credits being reported
Payroll checked Payroll records and PAYG withholding Payg figures should agree with the underlying payroll records
Accounting basis confirmed Cash or non-cash GST reporting Determines when relevant transactions are reported
Final BAS reviewed Bas figures compared with accounting reports and prior periods Unexpected differences can be investigated before lodgement

What Should You Check on Sales Before Lodging a BAS?

Do not assume that every dollar of revenue shown in your profit and loss report attracts GST in exactly the same way.

When Reviewing Sales, Consider Whether:

  • All sales for the relevant period have been recorded
  • Sales have been included in the correct BAS period
  • The correct GST code has been applied
  • Gst-Free or other non-taxable transactions have been treated correctly
  • Credit notes and refunds have been entered correctly
  • Large or unusual transactions need additional checking.

This review is particularly useful if the GST reported appears significantly different from your normal trading pattern.

What Should You Check on Business Expenses?

Business expenses also need to be reviewed before GST credits are included in the BAS.

A payment appearing in a business bank account does not automatically mean the business can claim GST on the full amount.

Check:

  • Whether GST was included in the purchase
  • Whether the supplier and transaction have been recorded correctly
  • Whether the expense is business-related
  • Whether any private component needs to be accounted for
  • Whether the GST code in the accounting system is correct
  • Whether supporting documentation is available where required.

Examples that commonly require additional attention include bank fees, wages, loan transactions, owner drawings, some insurance transactions and purchases with a private-use component. Different transactions can have different GST treatment, so the accounting code should reflect the actual nature of the expense.

How Do Payroll and PAYG Affect a BAS?

If your business employs staff, PAYG withholding may form part of your activity statement.

Before completing the BAS, compare the payroll figures in your accounting or payroll system with the amounts being reported. Check that pay runs for the full period have been processed and that corrections or adjustments have been reflected correctly.

Payroll, GST and bookkeeping are related but separate parts of the accounting process. Our guide to bookkeeping vs payroll explains the distinction in more detail.

Can You Prepare and Lodge Your Own BAS?

Yes. A business owner can prepare and lodge their own BAS.

For a business with relatively straightforward transactions and well-maintained records, this may be manageable. The key issue is whether the information being reported is accurate, not simply whether the form can be completed.

Preparing Your Own BAS Can Become Harder When the Business Has:

  • A high volume of transactions
  • Multiple bank accounts or credit cards
  • Employees and payroll obligations
  • Mixed GST treatments
  • Asset purchases or disposals
  • Private and business expenditure that needs to be separated
  • Unreconciled historical transactions
  • More complex bookkeeping or tax requirements.

Keeping accurate records throughout the quarter or month can reduce the work required when BAS time arrives.

Can a Bookkeeper Prepare Your BAS?

A bookkeeper can assist with the financial records that support BAS preparation, including recording transactions, reconciling accounts and maintaining accounting systems.

However, providing BAS services for a fee is regulated in Australia. Where the work constitutes a BAS service, the person or entity generally needs to be registered with the Tax Practitioners Board unless an exemption applies.

The scope of a BAS service can include determining or advising a client about obligations under a BAS provision, or representing a client in dealings with the ATO in relation to those obligations.

Our guide explains in more detail whether a bookkeeper can lodge a BAS.

What Is a BAS Agent?

A BAS agent is a tax practitioner registered with the Tax Practitioners Board to provide BAS services within the scope of their registration.

Registration requirements include relevant qualifications and experience, along with other professional requirements set by the Tax Practitioners Board.

If you are paying someone specifically to provide BAS services, you can check their registration on the Tax Practitioners Board’s public register. You can also read our explanation of what a BAS agent is.

What Happens if You Make a Mistake on a BAS?

A BAS error does not necessarily mean the original statement must always be handled in the same way. The appropriate correction depends on the type of error and the circumstances.

The ATO allows some GST errors from an earlier tax period to be corrected on a later BAS where the relevant conditions are satisfied. Other errors may need to be dealt with by revising the earlier statement or using another correction process.

For example, the ATO distinguishes between credit errors, where too much GST was reported or paid, and debit errors, where too little GST was reported or paid. Different conditions can apply when correcting these errors.

If You Identify an Error, First Establish:

  • What caused the mistake
  • Which BAS period is affected
  • Whether the underlying bookkeeping also needs to be corrected
  • Whether the error qualifies to be corrected on a later BAS
  • Whether the original BAS needs to be revised instead.

The ATO provides current guidance on correcting GST errors. Where the correct treatment is unclear, consider obtaining professional assistance before changing previously lodged figures.

How Can Better Bookkeeping Make BAS Preparation Easier?

The easiest time to prepare for your next BAS is throughout the reporting period, not on the day it is due.

Regular bookkeeping allows transactions to be entered, coded and reconciled while the supporting documents and business context are still readily available.

A Regular Bookkeeping Process May Include:

  • Processing transactions throughout the month
  • Matching customer payments to invoices
  • Allocating supplier payments correctly
  • Reconciling bank and credit card accounts
  • Reviewing accounts receivable and payable
  • Maintaining payroll records
  • Checking GST coding
  • Reviewing reports before the end of the BAS period.

This does more than support BAS preparation. Current financial records can also give a business owner a clearer view of cash flow, outstanding debts, expenses and financial performance.

M2 Corporate’s Bookkeeping services support businesses with ongoing transaction processing, reconciliations, financial records and BAS and IAS readiness. The level of support required will depend on the business, its systems and the complexity of its financial records.

When Should You Get Help with BAS Preparation?

Professional support may be worth considering when you are unsure whether the underlying records are correct or the BAS involves transactions you do not know how to treat.

Common Situations Include:

  • Your bookkeeping has fallen several months behind
  • Bank or credit card accounts will not reconcile
  • You are unsure which GST codes should apply
  • Your BAS figures differ significantly from your accounting reports
  • You have recently registered for GST
  • You have started employing staff
  • You have significant asset purchases or disposals
  • You have discovered errors in a previously lodged BAS
  • Your business has become more complex as it has grown.

BAS is one part of the wider accounting and tax obligations of running a business. Our guide to tax compliance for Australian businesses covers several other areas business owners may need to manage.

FAQs

What Do I Need to Prepare My BAS?

You generally need complete financial records for the reporting period, including sales, purchases, bank transactions, GST information and any relevant payroll or PAYG records. The exact records required depend on the obligations included on your BAS.

How Do I Prepare a BAS for the First Time?

Start by confirming the period covered by the statement and the obligations shown on it. Bring your bookkeeping up to date, reconcile the relevant accounts, review GST coding and payroll records, then compare the BAS figures with your accounting reports before lodging.

How Do I Calculate BAS?

There is no single calculation for the whole BAS because it can contain several tax obligations. For GST, the net position generally takes into account GST payable on taxable sales and eligible GST credits on business purchases. PAYG and other obligations can then affect the overall BAS amount.

What Documents Do I Need for a BAS?

Documents may include sales invoices, supplier invoices, receipts, bank statements, credit card records, payroll reports and other records supporting the transactions reported for the period. What you need depends on the nature of your business and the BAS labels you must complete.

Do I Need to Reconcile My Bank Account Before BAS?

Reconciliation is a useful part of BAS preparation because it helps identify missing, duplicated and unmatched transactions before you rely on your accounting reports. Business.gov.au also recommends reconciling BAS figures with your records before lodgement.

Can I Do My BAS Myself?

Yes. Business owners can prepare and lodge their own BAS. Whether this is practical depends on the quality of the bookkeeping and the complexity of the transactions and obligations involved.

Can a Bookkeeper Lodge My BAS?

A bookkeeper may be able to provide BAS services if they are appropriately registered or the work falls within an applicable exemption. BAS services supplied for a fee are regulated by the Tax Practitioners Board.

Does BAS Include Payroll?

A BAS can include PAYG withholding relating to payments such as employee wages. The exact sections appearing on the BAS depend on the business’s registrations and obligations.

Does Every Business Need to Lodge a BAS?

No. Whether a business needs to lodge activity statements depends on its tax registrations and obligations. For example, GST-registered businesses generally have GST reporting obligations, while other registrations can also create activity statement requirements.

How Often Do Businesses Lodge BAS?

The reporting cycle depends on the business’s circumstances and ATO requirements. BAS reporting may be monthly, quarterly or, in some circumstances, annually. Check the reporting period and due date shown for your business rather than assuming the same cycle applies to every business.

What Happens if My BAS Figures Look Wrong?

Do not lodge solely because the figures came from accounting software. Recheck reconciliations, transaction dates, GST codes, sales, purchases and payroll records. If the difference cannot be explained, professional assistance may help identify the underlying issue.

Can I Correct a BAS After It Has Been Lodged?

Yes, BAS errors can be corrected, but the appropriate process depends on the error. Some GST errors may be corrected on a later BAS if ATO conditions are met, while other errors may require revision of the original statement.

Get Your Bookkeeping Ready for BAS

A smoother BAS process starts well before the lodgement deadline. Keeping transactions current, accounts reconciled and GST coding accurate throughout the reporting period makes it easier to review the figures and identify problems before they are reported.

M2 Corporate works with businesses in Perth and across Australia through Accounting & Tax and Bookkeeping services. Support can range from maintaining day-to-day financial records through to helping businesses manage their broader accounting and reporting requirements.

If your accounts are behind, your BAS figures are not reconciling or you would like support maintaining your bookkeeping throughout the year, speak with M2 Corporate about the level of support that may be appropriate for your business.

This information is general only and does not take into account your objectives, financial situation or needs. Tax and BAS requirements depend on your circumstances and may change over time.
Read more

How to Set Up Xero for a Small Business in Australia

Accountant instructing a small business how to set up Xero

To set up Xero properly, you need more than a new account and a bank connection. Your Chart of Accounts, opening balances, bank feeds, payroll, invoice settings, tracking and existing financial data should all reflect how your business actually operates.

A well-planned setup makes bookkeeping easier and gives you more useful financial information from the start. This guide explains the main steps Australian small businesses should consider when setting up Xero.

Quick summary

  • Set up your organisation and financial settings first.
  • Build or customise your Chart of Accounts around your business.
  • Enter accurate opening balances if the business is already trading.
  • Connect your business bank accounts and bank feeds.
  • Configure payroll correctly if you employ staff.
  • Set up branded invoices and payment settings.
  • Use tracking categories where they will improve reporting.
  • Carefully migrate existing accounting data if moving from another system.

What should you set up in Xero first?

Start with the foundations of your accounting file before worrying about day-to-day transactions.

Your organisation details, financial settings and accounts affect how information is recorded and reported later. Taking time to get these settings right can reduce the need to clean up your accounts after months of trading.

The exact setup will differ between businesses. A consulting firm, construction company and retailer may all use Xero, but the accounts and reporting structure each business needs can be very different.

Accounting showing a small business the Xero dashboard

1. Set up your Chart of Accounts

Your Chart of Accounts determines how transactions are categorised in Xero. It typically separates items such as revenue, expenses, assets, liabilities and equity into accounts that can then be used in your financial reports.

Xero provides a starting structure, but the accounts can be customised to suit your business.

For example, a generic sales account may be enough for one business. Another business may want separate revenue accounts for different services so management can see which parts of the business are generating income.

The aim is not to create as many accounts as possible. Your Chart of Accounts should provide useful information without making bookkeeping unnecessarily complicated.

If you want the accounting structure configured around your business, our Xero setup services in Perth include a custom Chart of Accounts as part of eligible setup and migration packages.

2. Enter the correct opening balances

If you are setting up Xero for an existing business, your accounting file needs an accurate starting point.

Opening balances can include amounts such as:

  • business bank balances
  • outstanding customer invoices
  • unpaid supplier bills
  • business loans
  • assets and liabilities
  • GST and tax balances
  • equity balances.

This is one of the main differences between starting Xero for a brand-new business and migrating an existing business into Xero.

Incorrect opening balances can flow through to later reports, which is why existing accounting records should be reviewed carefully before they are transferred.

3. Connect your bank accounts and bank feeds

Bank feeds allow supported bank transactions to flow into Xero so they can be reviewed and reconciled against your accounting records.

Rather than manually entering every transaction from a bank statement, connecting the relevant business accounts can make ongoing bookkeeping more efficient.

When setting up Xero, check that you have included every account that forms part of the business records, such as:

  • operating accounts
  • savings accounts
  • business credit cards
  • loan accounts where relevant
  • payment accounts used by the business.

You should also make sure the account in Xero corresponds to the correct real-world bank account before transactions begin flowing through.

4. Configure payroll if you employ staff

Australian employers also need to consider payroll when setting up Xero.

Depending on your business and Xero plan, payroll setup can involve employee information, pay rates, pay calendars, leave settings, tax details, superannuation and Single Touch Payroll reporting.

This is an area where correct setup matters. Payroll data is not simply an internal record. Australian employers use Single Touch Payroll to report relevant payroll information to the ATO.

If payroll is part of your Xero implementation, check the configuration before processing your first live pay run.

5. Set up your invoice template

Your Xero setup should also reflect how customers interact with your business.

A branded invoice template can include your business details and provide a consistent format for invoices issued through Xero.

Review details such as:

  • business name and contact information
  • ABN details where relevant
  • logo and branding
  • payment terms
  • bank or payment details
  • standard invoice wording.

Setting this up at the beginning helps avoid repeatedly correcting invoice details after you start using the system.

6. Decide whether you need tracking categories

Tracking categories can be useful when you want to understand the performance of different areas within the same Xero organisation.

For example, a business operating from several locations may want to compare each location. Another business might want to report on separate departments or cost centres.

The key question is whether the extra information will actually help you make decisions.

Adding tracking simply because the feature exists can make transaction processing more complicated. When it is planned around useful management reporting, however, it can give business owners much clearer information.

7. Review your dashboard and reporting requirements

Your accounting software should help you understand the business, not simply store transactions.

Consider what information you regularly need to see. This might include outstanding invoices, bills, bank balances, cash flow or particular areas of business performance.

The way your accounts and tracking are configured will also affect the quality of your reports. This is why accounting structure and Xero configuration should be considered together rather than treated as separate jobs.

8. Migrate existing data carefully

If you are moving from another accounting platform or desktop accounting package, decide what information needs to come across to Xero.

Depending on the migration, this can include:

  • opening balances
  • current accounting data
  • customer and supplier contacts
  • fixed asset information
  • bank accounts
  • outstanding invoices and bills.

A migration should leave you with a usable Xero file that agrees with the financial records you are moving from.

We offer a Desktop to Xero migration service for businesses moving from traditional desktop accounting software, including opening balances, current accounting data, contacts, fixed assets and team logins.

9. Give the right people access

Once the accounting file is configured, consider who needs access and what they need to do inside Xero.

This can include business owners, internal accounts staff, bookkeepers and accountants.

Access should be set up intentionally rather than sharing one login between several people. This helps keep responsibilities clearer and allows the business to manage who can work with its accounting information.

Should you set up Xero yourself or use an accountant?

A straightforward new business may be comfortable handling parts of its own Xero setup. The more existing data, employees, reporting requirements or business complexity you have, the more valuable professional setup can become.

Getting help can be particularly useful when:

  • you are moving from another accounting system
  • you have existing balances that need to be transferred
  • you are unsure how to structure your Chart of Accounts
  • you need payroll configured
  • you want meaningful management reporting
  • different business divisions or locations need to be tracked
  • your internal accounts team needs ongoing Xero support.

We are a Xero Gold Partner and provides setup, migration and ongoing Xero support for Perth businesses. Rather than treating Xero as a standalone piece of software, we can configure it around how your business records, manages and uses its financial information.

You can also combine Xero with ongoing bookkeeping services if you want support keeping transactions, reconciliations and financial records up to date after the initial setup.

What does professional Xero setup cost?

We offer different Xero packages depending on where your business is starting from:

  • New Business Xero Setup: $500 one-off
  • Desktop to Xero: $1,650 one-off
  • Xero Support: $250 per month
  • Custom to Xero: custom conversion option shown from $0

The right option depends largely on whether you are starting fresh, moving existing accounting records into Xero or already using Xero and needing ongoing assistance.

View the full inclusions and pricing for Xero Setup Perth.

M2 Corporate accounting awards and professional recognition

FAQs

How long does it take to set up Xero?

The time required depends on your business. A new business with no existing accounting records is generally simpler to set up than an established business that needs opening balances, contacts, assets and transaction data migrated from another system.

Can I set up Xero myself?

Yes. Business owners can set up Xero themselves. Professional assistance can be useful when you need to migrate existing records, configure payroll, customise your Chart of Accounts or structure reporting around a more complex business.

What information do I need before setting up Xero?

Useful information can include your business details, bank accounts, existing accounting records, opening balances, employee payroll information, invoice details and the reporting structure you want to use.

Do I need a custom Chart of Accounts in Xero?

Not every business needs a highly customised Chart of Accounts, but the account structure should reflect how your business operates and the financial information you need to report on.

Can I move from desktop accounting software to Xero?

Yes. Existing businesses can migrate accounting information into Xero. The information transferred depends on the existing system and the scope of the migration, but it can include opening balances, current accounting data, contacts and fixed asset information.

Can an accountant help after Xero has been set up?

Yes. We offer ongoing Xero Support from $250 per month for businesses with internal accounts teams that need help with Xero, Xero Add Ons and accounting queries.

Need Help Setting Up Xero?

A good Xero setup gives your business a cleaner starting point for bookkeeping, payroll and financial reporting. We can help you set up a new Xero organisation, migrate an existing accounting system or provide ongoing support to your internal accounts team.

Learn more about our Xero Setup Perth services or book a free strategy session with our team.

Read more

How to Establish a Trust in Australia

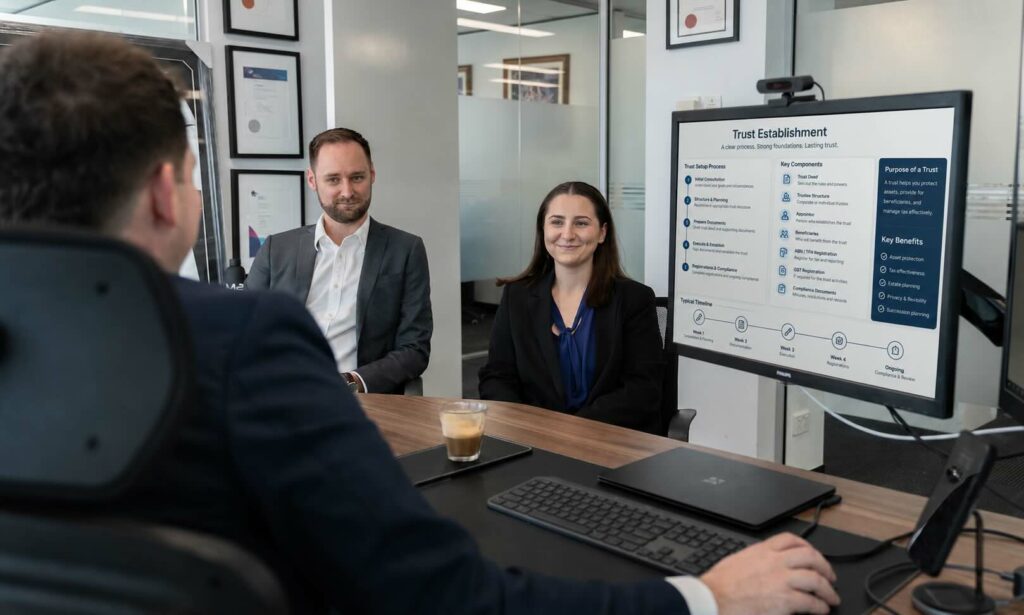
Mace Turco discussing trust establishment during a strategy meeting

To establish a trust in Australia, you need to choose the right type of trust, appoint a trustee, identify the beneficiaries, prepare and execute a trust deed, complete the required tax registrations and set up proper financial records.

A trust can support business ownership, investing, succession planning and asset management. However, it must be set up correctly from the beginning. The trustee will have legal, tax and record-keeping responsibilities, so professional accounting and legal advice should be obtained before documents are signed or assets are transferred.

(more…)

Read more

How Much Is Company Registration?

Business advisors discussing corporate compliance

Company registration in Australia usually costs from $611 in ASIC fees for a standard proprietary company with share capital, plus any professional setup fees if you use an accountant or advisor. At M2 Corporate, company establishment starts from $1,500 one-off.

For many business owners, the real cost is not just the ASIC fee. It also includes getting the structure, registrations, tax setup, company constitution, consent documents, registers and ownership records right from the start.

(more…)

Read more

How an Accountant Can Help a Business Succeed

Accountant explaining to a man and woman how accountants help businesses succeed

The right business accountant becomes a trusted partner. They help you understand your numbers, make better decisions, plan ahead, and avoid costly mistakes. They bring structure, clarity, and confidence to your business.

Running a business involves constant decision-making. Hiring staff, pricing services, managing expenses, investing in growth, and planning for the future all depend on having accurate and reliable financial information.

Without that clarity, business owners often rely on instinct or incomplete data. That can lead to poor decisions, missed opportunities, and unnecessary risk.

An accountant provides structure. They ensure your financial information is accurate, up to date, and useful. More importantly, they help you understand what the numbers actually mean.

At M2 Corporate, we work with businesses at every stage, from early setup through to growth, management, and exit. Our focus is not just on compliance. It is on helping business owners make informed decisions that support long term success.

Quick Summary

  • An accountant helps you stay compliant and avoid costly mistakes.
  • They provide clear financial insights to support better decisions.
  • They help manage cash flow, profitability, and risk.
  • They support planning, forecasting, and business growth.
  • They act as a trusted advisor, not just a service provider.
  • As your business grows, their role becomes more strategic.

1. Keeping Your Business Compliant and Protected

One of the most immediate ways an accountant helps a business succeed is by ensuring compliance.

This includes tax obligations, reporting requirements, payroll compliance, and regulatory responsibilities. While this may seem basic, it is critical. Mistakes in these areas can result in penalties, audits, and reputational damage.

Key Compliance Areas Accountants Manage

  • Preparation and lodgement of tax returns
  • BAS, GST, and PAYG obligations
  • Payroll and superannuation compliance
  • Financial statement preparation
  • ASIC and corporate compliance requirements

Getting these fundamentals right creates a stable foundation. It allows business owners to focus on growth without worrying about avoidable compliance issues.

2. Improving Cash Flow and Financial Control

Cash flow is one of the most common reasons businesses struggle. Even profitable businesses can fail if they run out of cash at the wrong time.

An accountant helps you manage cash flow by providing visibility and structure.

How Accountants Improve Cash Flow

  • Tracking incoming and outgoing cash accurately
  • Identifying timing gaps between income and expenses
  • Creating cash flow forecasts
  • Highlighting potential shortfalls early
  • Advising on payment terms, costs, and working capital

Simple example: If your business invoices clients on 30-day terms but pays suppliers within 7 days, your accountant will identify the gap and help you adjust your approach before it becomes a problem.

3. Providing Clear Financial Insights

Numbers on their own do not drive success. Understanding those numbers does.

An accountant translates financial data into insights you can act on. This includes profitability, cost control, pricing, and performance across different areas of your business.

Key Financial Insights You Gain

  • Which products or services are most profitable
  • Where costs are increasing or out of control
  • How efficiently your business is operating
  • Whether your pricing supports sustainable margins
  • How your performance is trending over time

This level of clarity allows you to make decisions based on facts rather than guesswork.

4. Supporting Better Business Decisions

Every business decision has a financial impact. Hiring staff, expanding operations, investing in equipment, or entering new markets all carry risk.

An accountant helps you assess these decisions before you commit.

Examples of Decisions an Accountant Can Support

  • Can you afford to hire another employee?
  • Should you increase prices or adjust your cost structure?
  • Is it the right time to expand?
  • Should you invest in new systems or equipment?
  • What is the financial impact of a new opportunity?

Instead of relying on assumptions, you can model different scenarios and understand the likely outcomes.

5. Helping With Business Planning And Strategy

As your business grows, planning becomes more important. You need to think beyond day to day operations and focus on where the business is heading.

An accountant plays a key role in this process by helping you set realistic goals and build a plan to achieve them.

Areas Where Accountants Support Planning

  • Budget setting and financial planning
  • Revenue and cost forecasting
  • Growth strategy support
  • Scenario modelling for different outcomes
  • Setting KPIs and performance targets

This moves the role from reactive to proactive. Instead of reviewing what has already happened, you are planning what comes next.

If your business is at this stage, our business advisory services are designed to help you step back, assess your position, and move forward with clarity.

6. Improving Profitability And Performance

Growth alone does not guarantee success. A business can grow quickly while becoming less profitable.

An accountant helps you focus on both growth and profitability.

Ways Accountants Improve Profitability

  • Identifying low-margin products or services
  • Highlighting unnecessary or excessive costs
  • Improving pricing strategies
  • Analysing gross and net profit margins
  • Tracking performance against targets

Simple example: A business may increase revenue by 20%, but if costs increase by 30%, profitability declines. An accountant ensures you are not just growing, but growing sustainably.

7. Supporting Business Growth

As businesses expand, financial complexity increases. More staff, higher costs, larger transactions, and new risks all come into play.

An accountant helps you manage this growth without losing control.

How Accountants Support Growth

  • Ensuring systems and processes scale with the business
  • Providing financial forecasts for expansion
  • Supporting funding and investment decisions
  • Helping manage increasing operational complexity
  • Maintaining clear reporting as the business grows

This support becomes especially valuable when decisions become larger and the margin for error reduces.

8. Acting As A Strategic Business Partner

One of the most important ways an accountant helps a business succeed is by acting as a strategic partner.

This means working alongside the business, not just delivering reports. It involves understanding your goals, your challenges, and your industry.

At this level, the accountant is involved in ongoing discussions about performance, direction, and decision-making.

This is often where businesses move beyond basic accounting into advisory and CFO-level support.

Our outsourced CFO services provide this level of support, offering deeper insight and financial leadership without the cost of a full-time hire.

9. Helping You Avoid Costly Mistakes

Mistakes in business can be expensive. Poor pricing, weak cash flow management, incorrect tax treatment, or unplanned expansion can all impact your results.

An accountant helps identify risks early and guide you toward better decisions.

Common Mistakes Accountants Help Prevent

  • Underpricing products or services
  • Poor cash flow management
  • Incorrect tax handling
  • Overcommitting to growth without planning
  • Weak financial controls and reporting

By addressing these areas early, you reduce risk and improve long term stability.

10. Supporting Business Structure And Setup

The way your business is structured affects tax, risk, and future flexibility.

An accountant helps you choose the right structure from the beginning and adjust it as your business evolves.

Key Areas Of Support

  • Choosing the right business structure
  • Setting up accounting systems
  • Registering for tax and compliance requirements
  • Establishing financial processes from day one

Getting this right early avoids costly changes later.

11. Preparing For Exit Or Transition

At some point, many business owners consider selling, stepping back, or transitioning leadership.

An accountant plays a key role in preparing for this stage.

How Accountants Support Exit Planning

  • Ensuring financial records are accurate and reliable
  • Supporting valuation and due diligence
  • Identifying areas to improve before sale
  • Managing tax implications of a sale or transition

Planning ahead can significantly impact the value and outcome of the transition.

Learn more about business exit strategies here.

When Should You Engage An Accountant?

The earlier you engage an accountant, the more value they can provide.

Waiting until there is a problem limits what can be done. Engaging early allows for better planning, stronger systems, and more informed decisions.

As your business grows, your needs will change. What starts as basic compliance support can evolve into ongoing advisory and strategic partnership.

Final Thoughts

The question is not just how an accountant can help a business succeed, but how much value the right accountant can add over time.

From compliance and cash flow to strategy and growth, an accountant provides the structure and insight needed to make better decisions.

At M2 Corporate, we focus on building long term partnerships with our clients. We take the time to understand your business, provide clear advice, and support you at every stage of your journey.

If you are looking for a reliable, experienced team to help strengthen your financial position and support your growth, get in touch with our business accountants in Perth today for a free strategy session.

Read more

The Difference Between HR Advisor and HR Business Partners

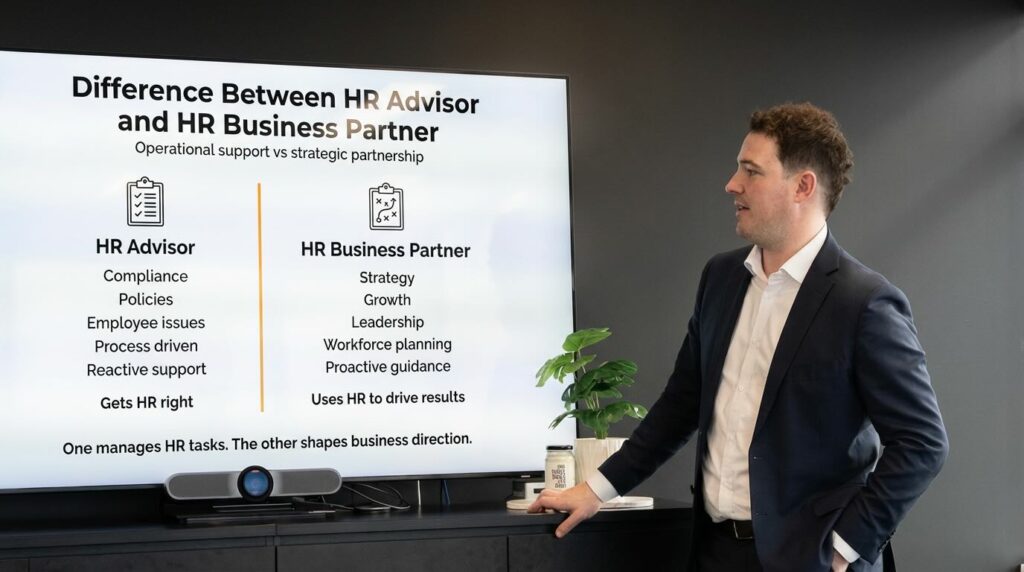
Screen showing the difference between HR advisors and HR business partners

Understanding the difference between HR advisor and HR business partner is important for business owners, managers, and leadership teams who want the right level of people support at the right time.

Although both roles sit within human resources, they serve very different purposes. One focuses on guidance, compliance, and process. The other focuses on strategy, performance, and long term business outcomes.

This guide explains the difference clearly, using plain language and practical examples, so you can decide which role your business actually needs.

(more…)

Read more

How Business Advisors Improve Operations

Business advisor explaining how they improve operations

Running a business today means juggling regulations, staff needs, cash flow pressures and constant demands for efficiency. Many owners feel stretched, and it becomes difficult to see where improvements should be made. A skilled business advisor brings clarity, structure and guidance that strengthens your operations and long-term stability.

Our advisors have brought together our decades of experience to help you understand the key functions of a business advisor in improving operations to help you streamline processes, improve financial visibility and make confident decisions.

(more…)

Read more

Tax Compliance for Businesses in Australia

Business advisor explaining tax compliance for businesses in Australia

Running a business is busy enough without tax surprises. This guide explains tax compliance for businesses in Australia in plain English, with clear steps, dates, and checklists you can use right away. It also points you to tools and support if you want a partner to keep everything on track.

(more…)

Read more

What Is Financial Advisory?

Mace Turco explaining what is financial advisory

Financial advisory helps business owners make better decisions with money. It brings together strategy, numbers, and practical actions so you can plan growth, protect assets, manage cash, meet obligations, and build long-term value. If you are still asking what is financial advisory, think of it as a trusted partnership that turns financial data into clear steps for your business.

(more…)

Read more

What is Business Advisory? [Comprehensive Guide]

Mace Turco explaining what is business advisory with a presentation

Business advisory is the practice of guiding business owners to make informed decisions that strengthen performance, reduce risk, and secure long-term growth. Unlike accounting, which looks back at what has already happened, advisory looks forward. It’s about translating numbers, trends, and operational data into strategies that work in the real world.

If you’ve ever wondered what is a business advisor, the role combines financial expertise, strategic thinking, and practical business management. Advisors don’t just report — they partner with you to build, review, and execute plans tailored to your goals.

(more…)

Read more